Treasury Bond Yields and Your Portfolio
Bonds: The Story Behind the Story
Publication date: October 8, 2026
The story is the increase in Treasury bond yields and the implications for stock and bond investors.
The impetus for this commentary is the swift uptick in the Treasury yield curve and the swift and substantial Treasury sell off. Both suggest a crisis of confidence in the ability of the U.S. to finance its ever-increasing long-term-debt without devaluing the dollar with persistent inflation. This is how we got here.
The yield curve plots the yield that bond investors demand for investing in U.S. Treasuries of various maturities at any point in time. Longer maturities carry more risk hence the upward slope of the curve. The following chart illustrates recent upward shifts in the curve.
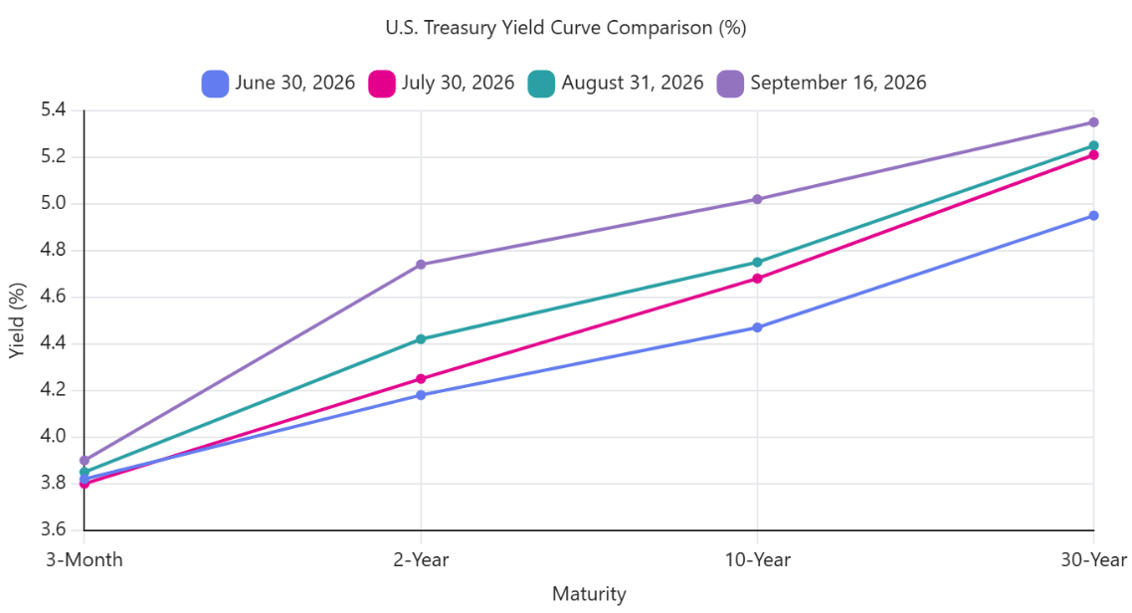
These shifts tell us that investors have been increasingly unwilling to buy Treasuries at previous yield levels. They demanded higher yields to compensate for a multitude of risks including rising oil prices which add to already persistent inflation, increased uncertainty regarding the Middle East, and the cost to finance the interest on $32.4 trillion of outstanding Treasury bonds held by the public.1 The annual interest cost on that debt is $1.1 trillion dollars, which is greater than annual spending on defense or Medicare. The Treasury sells bonds and T Bills at public auctions, competing in the capital markets with other investment options. It has had to increase yields to attract buyers.
Another $7.7 trillion of Treasuries are owned by other parts of the federal government, e.g., the Social Security and Medicare Trust funds, bringing the total national debt to $40.1 trillion.
Persistent and rising inflation directly erodes adjusted real returns of fixed rate bond interest payments and the power of bonds held to maturity. To maintain real returns, investors demand higher nominal yields. Investors require higher returns to hold long-term bonds than short-term bonds. That yield spread is the “term premium”.
